Sandisk is maybe the ultimate charts v fundamentals stock. The fundamentals are incredible.
We began fiscal year 2027 with another strong quarter, creating value for customers and shareholders and delivering results above guidance. Our strategy is working, and our execution is delivering strong results. Revenue for the quarter was $11 billion. Non-GAAP gross margin was 85.1% and non-GAAP earnings per share was $49.51. We generated $5.7 billion of adjusted free cash flow and returned $5 billion to shareholders through share repurchases. Our confidence in the long-term trajectory of the business is grounded in 3 enduring strengths: technology leadership, deep customer partnerships and disciplined financial management.
These strengths are reinforced by a structural increase in NAND demand, driven particularly by AI and by customer signals now extending beyond fiscal year 2030 through our new business models, our NBM partnerships. Together, they position us to invest with confidence in our technology road map, strengthen and expand our customer relationships, and deliver growing and durable free cash flow while returning capital to shareholders. It starts with our technology leadership. BiCS8 is the backbone of our current production portfolio and the industry benchmark for performance and density across TLC and QLC. BiCS8 introduced our CMOS Directly Bonded to Array, our CBA architecture, enabling the performance required by AI data center customers and establishing the framework for future generations.
Revenue for the first quarter was $11 billion, up 23% sequentially and 378% year-over-year. This compares favorably with our guidance range of $10.3 billion to $10.8 billion. Both volume growth and higher pricing contributed to revenue growth, with approximately 60% of the increase attributable to volume growth and 40% to higher pricing. Data center revenue was $4.8 billion, up 61% sequentially, outpacing estimated market growth for the quarter. Our leading products and strong customer partnerships, including 3 U.S. hyperscalers, underpin our continued expansion in this fast-growing end market.
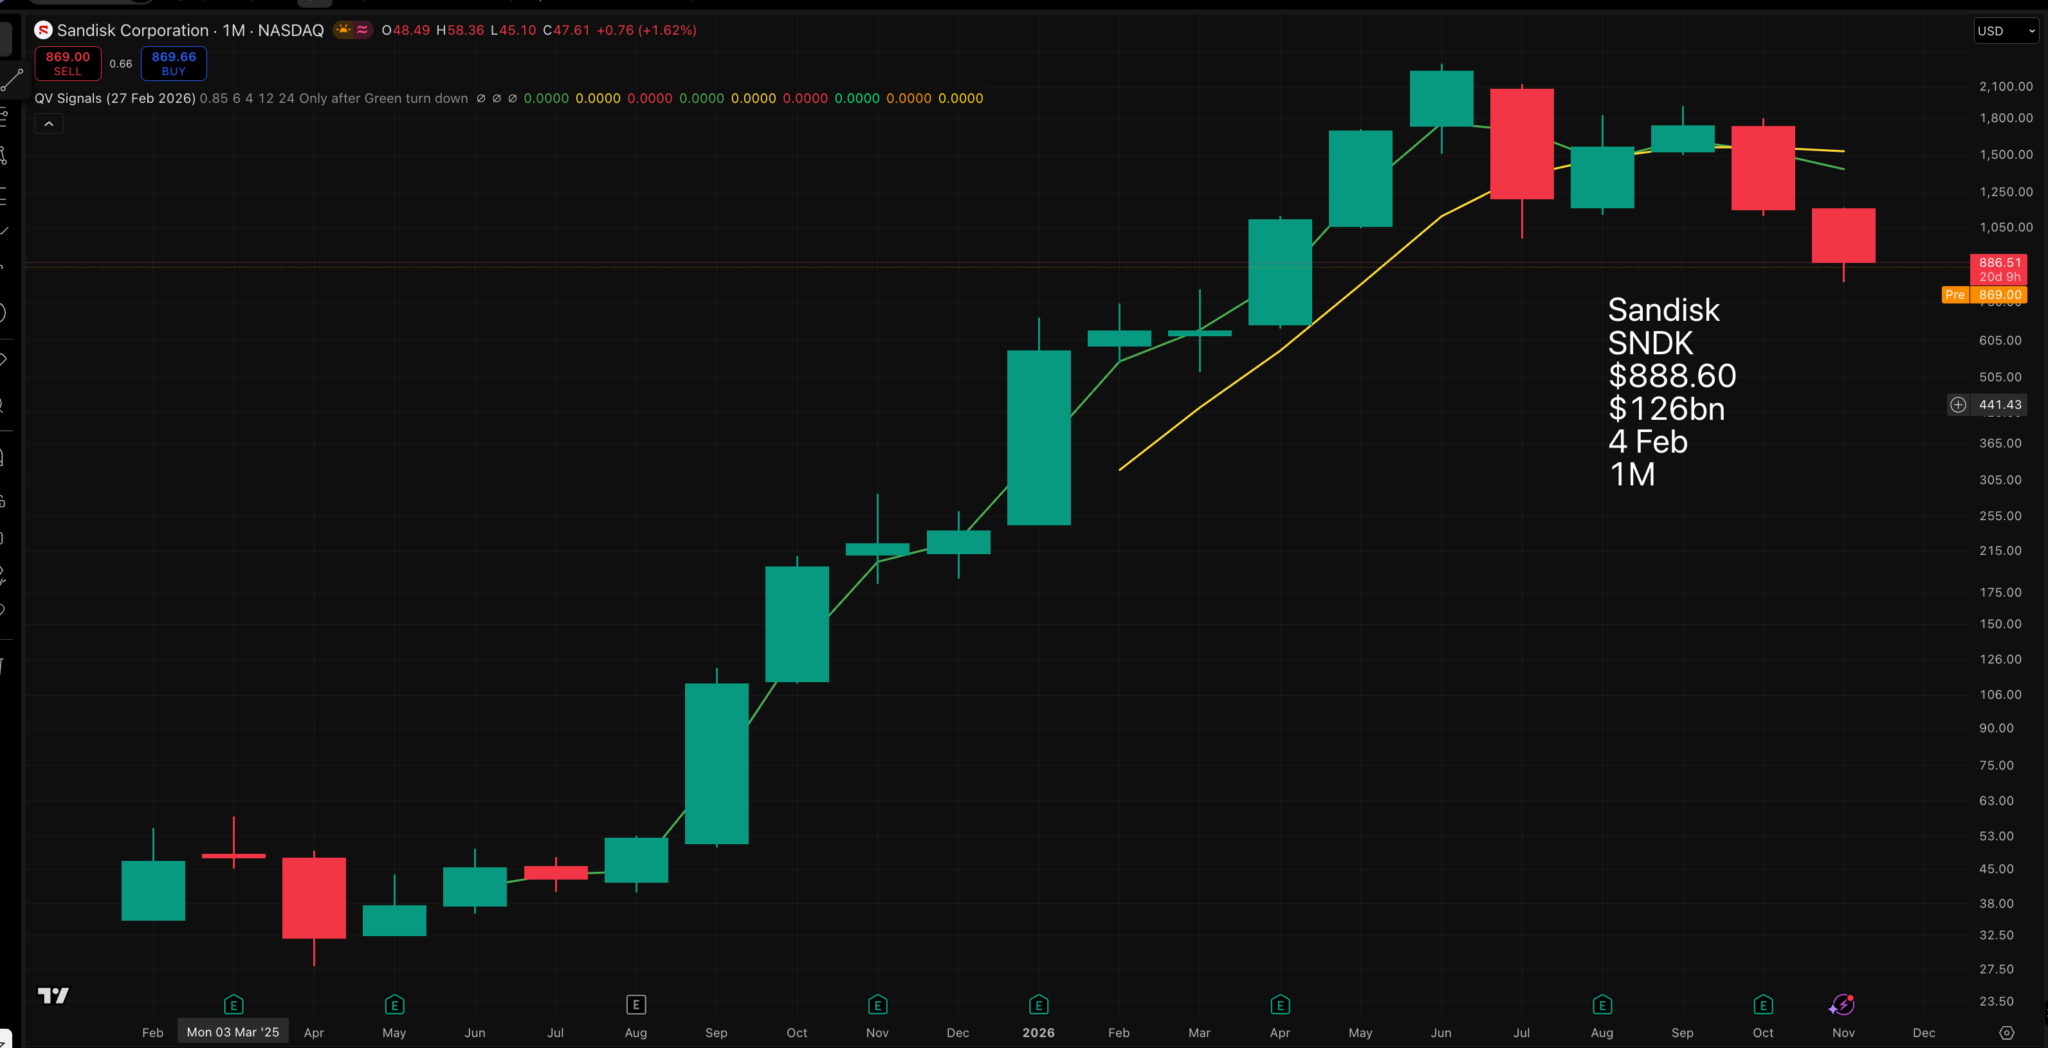
This company is running so hot it is in danger of melting yet the shares are in free fall. The chart shows a clear breakdown from a significant top area. This is even though the company is highly profitable, is generating massive free cash flow to fund ever larger share buybacks and on annualised sales of $44bn it is currently valued at less than three times sales. What is going on?
I have never seen such a bizarre contradiction between the message from the charts and the message from the fundamentals.
It is interesting to get AI’s thoughts on what is happening because reading between the lines I suspect AI is as baffled as I am.
Fears of an Impending Downcycle: Despite posting massive revenue growth (such as $11 billion in Q1 with high gross margins) driven by explosive AI data center demand, market sentiment has been rattled by concerns that NAND pricing is nearing its cyclical peak. Bears and short-term investors worry that a massive capacity buildout between 2027 and 2029 will flood the market and trigger a sharp downturn.
Commodity-Cyclical Perception: Wall Street often treats memory and flash-storage providers like commodity-driven cyclical plays. Even though the company is highly profitable, generates massive free cash flow, and is aggressively buying back shares, memories of past brutal downcycles leave investors hesitant to reward them with high valuation multiples.
Recent Volatility and Profit-Taking: After scaling massive heights earlier in the year, the stock has experienced heavy drawdowns alongside broader tech and memory sector corrections, leaving it sharply down from its all-time highs despite trading at a low price-to-earnings (P/E) ratio.
If this funk-based sell-off proves overdone and the negative chart is a temporary phenomenon then $-cost averaging these shares would be a bold and potentially hugely profitable strategy. In a nutshell AI is saying the shares are falling because investors are worried. Duh! That is obvious, but do those worries have any merit. AI doesn’t have a clue.
A simpler explanation of why the shares are falling could be because they rose so much before. Terrified investors are rushing to lock in huge paper profits and this madness of crowds panic could end by making the shares far too cheap, insanely cheap even.
Strategy – Time To Be Bold
It is difficult for me because I am a chartist at heart so it sticks in the craw to buy into a bearish chart but, if Sandisk is to avoid a bankruptcy, which is not remotely on the horizon given the latest incredible results and the super-strong balance sheet then accumulating these shares into weakness seems like a betting against the crowd strategy that could win big in the end.
The shares will begin trading ex an 8 for 1 share split on 20 November.